Owners don’t usually sell at the top of a rent cycle. They hold, push rents and refinance. So when an owner lists one of the city’s biggest rental buildings while rents are still breaking records, it’s worth asking what they see.
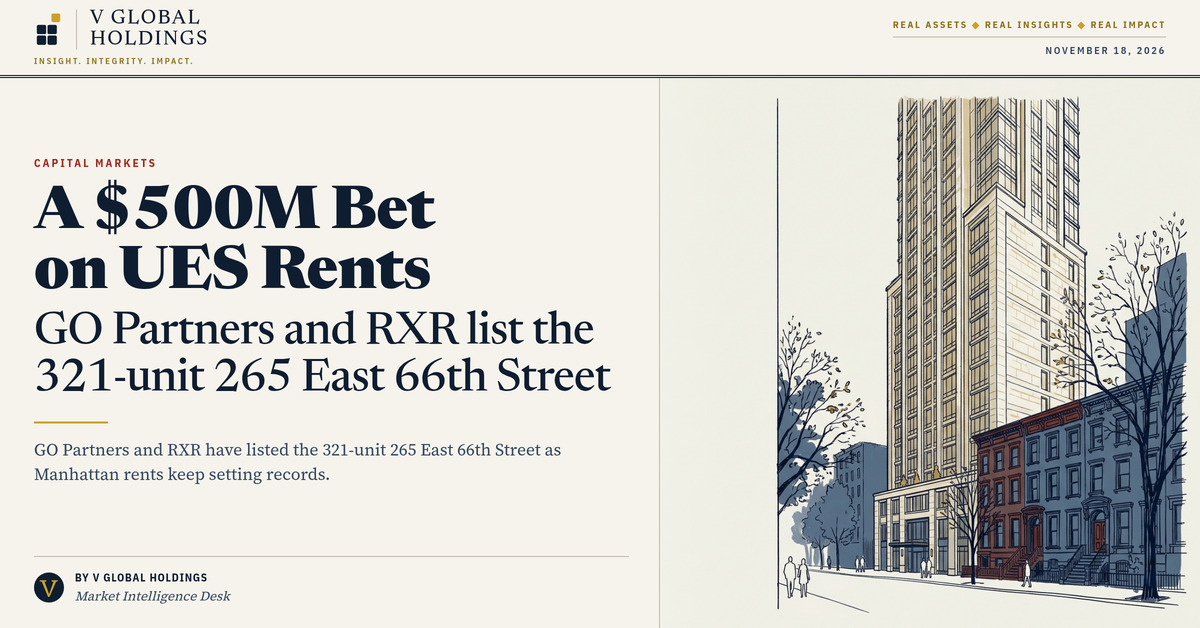
That’s the setup on the Upper East Side. GO Partners, the firm run by Josh Gotlib and Meyer Orbach, has listed 265 East 66th Street for sale with Scott Rechler’s RXR, The Real Deal‘s Rich Bockmann reported on Nov. 17. The target is about $500 million, which would make it one of the year’s biggest Manhattan multifamily deals.
Below: what’s for sale, the basis math in one table, the rent story the sellers are pitching, and what I think a buyer actually has to believe at that price.
What’s on the Block
The property is a 321-unit rental asset with two parts:
- A 47-story tower with 301 apartments
- 20 rental townhouses
A buyer can take it as a package or as two separate pieces. The townhouses could also be converted into single-family homes. That split is the most interesting part of the offering to me. It gives a buyer two ways to win.
Newmark is running the sale with a team led by Adam Spies, Adam Doneger and Willis Robbins. A representative for GO Partners declined to comment.
The Basis Math
GO Partners bought the tower and townhouses for $425 million in 2023. That purchase was one piece of its $1.66 billion acquisition of a multifamily portfolio from Stefan Soloviev’s Solow Building Company.
In January 2026, RXR bought a 45 percent stake in the property at a $435 million valuation.
My math: here is where a $500 million price would land against those two marks.
| Benchmark | Value | Gap to $500M | Change |
|---|---|---|---|
| GO purchase (2023) | $425M | +$75M | +17.6% |
| RXR stake valuation (Jan. 2026) | $435M | +$65M | +14.9% |
| Target price (Nov. 2026) | ~$500M | — | — |
| Per unit at $500M (321 units) | ~$1.56M | — | — |
Two caveats before anyone calls that a profit. First, $500 million is a target, not a closed price. Second, the table ignores renovation spending, carry and fees, none of which TRD reported. It’s a basis comparison, not a return.
Even so, the direction is clear. The sellers believe the building is worth meaningfully more than it was 10 months ago, and they think a buyer will pay for it.
The Rent Story They’re Selling
The pitch rests on one number. In some recently renovated apartments, GO Partners has pushed rents from $75 per square foot to $130, according to a person familiar with the building.
My math: that’s roughly a 73 percent jump on renovated units.
The citywide backdrop helps. Manhattan average rents hit an all-time high of more than $6,300 in July, or more than $100 a foot. That extended an 18-month run of record rents.
TRD points to two forces behind it:
- Supply is constrained. The expiration of the 421a development tax break caused a multi-year pause in new construction.
- Demand is up. Higher interest rates have pushed would-be buyers back into the rental market.
A building already renting renovated units at $130 a foot is well above that $100 citywide average. My read: the offering is betting the gap between renovated and unrenovated units matters more than the citywide number.
Why Sell Now?
TRD doesn’t report a reason for the sale. Still, a few facts in the story are worth putting side by side.
GO Partners and RXR own this building separately from GO Residential, the REIT Gotlib and Orbach launched on the Toronto Stock Exchange in 2025 with a $410 million IPO.
As of August, GO Residential was poised to become Canada’s second-largest REIT through a planned acquisition of the 27-property H&R Real Estate Investment Trust. That deal fell apart when H&R’s shareholders voted it down. GO Residential has since filed a $72 million lawsuit against H&R.
My read: none of that ties the 66th Street sale to the H&R fight, and I won’t draw that line. What it does show is a sponsor that thinks in platforms and capital cycles, not single buildings. Selling a stabilizing asset into record rents is a classic way to show the market what your business plan is worth.
What a Buyer Has to Believe
At roughly $1.56 million a unit, a buyer isn’t paying for today’s rent roll. They’re paying for three bets:
- The renovation runway is real. The $75-to-$130 jump has to repeat across enough of the 301 tower units to justify the price.
- The supply gap lasts. If the post-421a construction pause keeps new rental supply tight, record rents have room to hold.
- The townhouses are an option, not a footnote. A buyer who can sell 20 converted single-family homes separately may be able to bring down the basis on the tower.
There’s also a structural question. Selling the tower and the townhouses separately could draw two different buyer pools: institutional rental capital for the tower and wealthy end users or small developers for the townhouses. My read: a split sale is where a seller might beat a package price, and that’s probably why Newmark is offering both.
The Line Every Bidder Will Underline
The offering memo puts the sellers’ thesis in one phrase.
“significant runway to increase rents at the property” — Newmark offering memo, as reported by The Real Deal
Every bidder will test that phrase against the rent roll. The ones who believe it will bid. The ones who think the renovated comps are the exception, not the rule, will sit this one out.
What This Means for Operators
If you own or manage Manhattan rentals, this deal is a price check on your own building.
- Separate renovated rents from in-place rents. The spread between them is what buyers are paying for, so track it unit by unit.
- Know your supply story. The 421a pause is a market-wide tailwind. Make sure your underwriting shows how long you expect it to last.
- Look for optionality in the asset. The 20 townhouses here give a buyer a second exit. Most buildings have something similar: retail, air rights, a unit mix that can be reconfigured.
- Watch where this prices. If 265 East 66th trades near $500 million, it sets a new reference point for luxury Upper East Side rentals.
The Bottom Line
GO Partners and RXR are testing whether record rents can be turned into a record price. The basis is known: $425 million in 2023 and $435 million at RXR’s January stake. The ask is about $500 million. The difference is the rent runway, and the market is about to say what it thinks that runway is worth.
I’ll be watching where the bids land, and whether the tower and townhouses go to one buyer or two.
Operators: when you underwrite a Manhattan rental today, how much of the price are you willing to pay for renovation upside you haven’t captured yet?