A trophy H&M Fifth Avenue leasehold is for sale, and the pricing is a lesson in itself. Manova Partners has put 589 Fifth Avenue, the H&M-anchored building, on the market for up to $300 million. It paid $365 million for the leasehold in 2019.
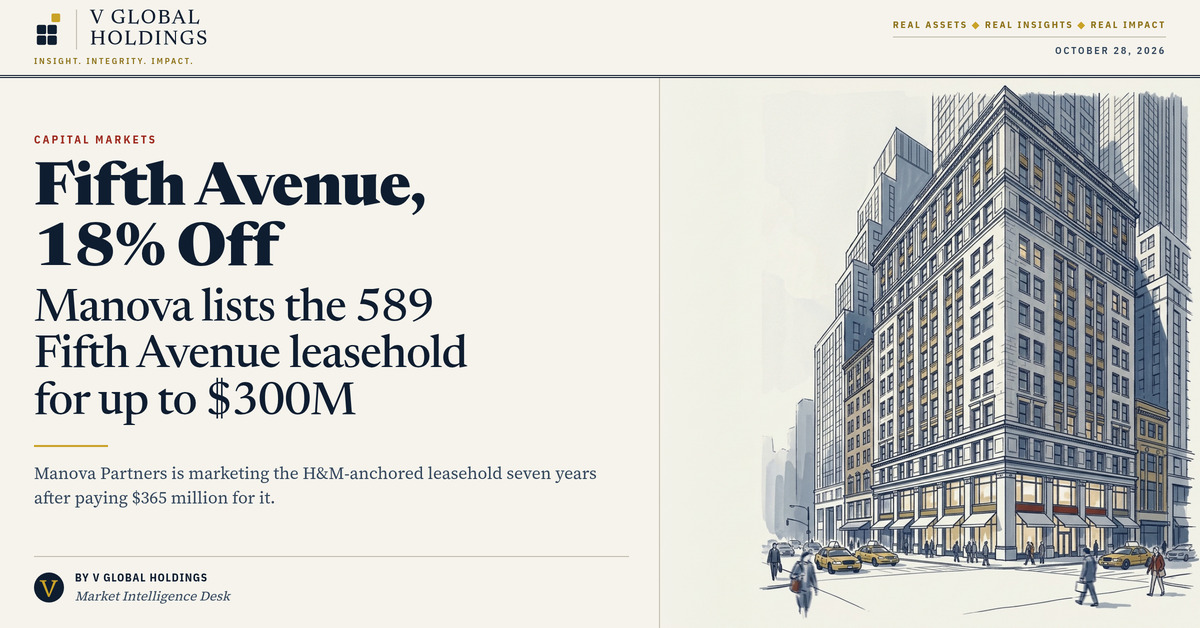
That’s an 18 percent markdown on one of the most visible retail corners in America.
If you underwrite Manhattan retail, lend against ground-leased assets, or wonder where the prime-corridor market really clears, this deal is worth ten minutes. I’ll go through what’s for sale, who’s circling it, the lender story underneath, and the one date that matters more than the asking price. By the end you’ll see why the buyer pool here isn’t the usual investor crowd. It’s retailers.
The Asset
Here’s what’s on the block, per TRD’s reporting:
- Address: 589 Fifth Avenue, Midtown Manhattan
- Interest for sale: the leasehold, not the fee
- Size: 184,000 square feet of office and retail
- Height: 17 stories
- Anchor: H&M, with a 68,000-square-foot flagship
- Anchor rent: about $319 per square foot, according to sources
- Anchor lease expiration: 2033
- Brokers: Newmark’s Adam Spies and Marcella Fasulo
- First reported by: Green Street’s Real Estate Alert
The leasehold traces back to 2019. That’s when GLL Real Estate Partners, then part of Australia’s Macquarie Group, signed a 99-year lease on the building. GLL spun off from Macquarie in 2024 and relaunched as Manova Partners. Same asset, new name on the door.
The Numbers That Matter
Put the two price points next to each other and the story writes itself.
| Metric | 2019 acquisition | 2026 ask |
|---|---|---|
| Leasehold price | $365M | up to $300M |
| Price per SF (my math) | ~$1,984 | ~$1,630 |
| Change | — | −18% |
| Senior loan at acquisition | $182M (Deutsche Pfandbriefbank) | — |
A few more figures I ran myself:
- H&M’s rent roll. At $319 a foot on 68,000 square feet, the flagship pays roughly $21.7 million a year. That’s my math on the reported rent, not a disclosed figure.
- Anchor share of the building. H&M’s box is about 37 percent of the total square footage. That’s a lot of the building’s value in one tenant’s hands.
- Original leverage. The $182 million loan was roughly half of the $365 million purchase price. Against a $300 million ask, the same loan would be about 61 percent.
- Remaining ground term. A 99-year lease signed in 2019 leaves about 92 years. Long enough that most buyers will price this like ownership, but the ground lease is still part of the deal.
“Several retailers are looking to buy the property with the goal of taking over H&M’s 68,000-square-foot space at the end of its lease in 2033, according to a source familiar with the matter.” — The Real Deal
Why Retailers, Not Investors
This is the part of the story I find most interesting.
The buyers reported to be circling 589 Fifth aren’t the usual capital allocators. According to a source cited by TRD, several retailers want the building so they can take over H&M’s space when its lease ends in 2033.
Think about what that says.
A retailer buying the leasehold isn’t underwriting a yield. It’s buying control of a flagship location, with an existing tenant paying the bills for seven more years. For a brand that wants a Fifth Avenue storefront, waiting on a lease expiration is a gamble. Buying the building turns it into a plan.
That changes the math on price. An investor looks at in-place income, rollover risk, and exit cap. A retailer looks at what it would cost to get that frontage any other way, and the honest answer on Fifth Avenue is often: you can’t.
So the 18 percent markdown may say less about the corridor than it first looks. Part of it reflects a seller with its own reasons to move. Part of it reflects who the natural buyer actually is.
The Lender Underneath
There’s a second thread here, and it runs through the capital stack.
The 2019 acquisition was financed with a $182 million loan from Deutsche Pfandbriefbank, according to property records. TRD notes what has happened to that lender since:
- In 2025, the bank said it would stop new lending in the U.S. to focus on Europe.
- It said it would securitize or sell its $4.6 billion U.S. portfolio.
- Its U.S. commercial real estate loans led to sizable losses, according to Bloomberg.
- It also lent to Signa Holding, René Benko’s collapsed Austrian company that once co-owned the Chrysler Building with RFR.
The reporting doesn’t say whether that exit is driving this sale. I won’t guess. But I’d want to know two things before bidding: where that loan stands today, and whether a buyer can assume it or has to bring fresh debt. When a lender is shrinking its U.S. book, a sale that pays off the loan can work out for everyone.
What I’d Take From It
Here’s how I read 589 Fifth as an operator:
- Prime isn’t immune. Even a flagship Fifth Avenue leasehold with a credit anchor is pricing below its 2019 basis.
- Know your buyer pool. For flagship retail, an end user can pay what an investor can’t. Brokers marketing to retailers aren’t being creative, they’re reading who the buyers are.
- The lease date is the asset. H&M’s 2033 expiration is the hinge. Before then, it’s a stable income play. After that, whoever controls the space decides what happens next.
- Read the lender’s situation too. A lender pulling back from the U.S. can change how flexible the seller is, even when nobody says so publicly.
- Leaseholds price differently. Even with roughly 92 years left, the ground lease affects financing, residual value and the buyer pool. Underwrite it, don’t skip past it.
If you’re thinking about Manhattan retail, this sale is a live read on the market. The ask is public. The clearing price will be more telling.
Your Move
Fifth Avenue retail is repricing, but not in the simple way the headline suggests. A retailer that can wait seven years for a flagship box might see $300 million as a fair price for the address. An investor running a 2033 rollover on a $319-a-foot anchor might see risk.
So here’s my question for operators and capital allocators: if you were bidding on 589 Fifth, would you price it on H&M’s in-place rent or on what a new retailer would pay for that frontage in 2033?
Tell me in the comments. And if you’re underwriting a ground-leased or retail-anchored asset in Manhattan and want a second read on the numbers, send me a message.
Source: The Real Deal.